The Holiday Rush Ends. The Bills Don’t.
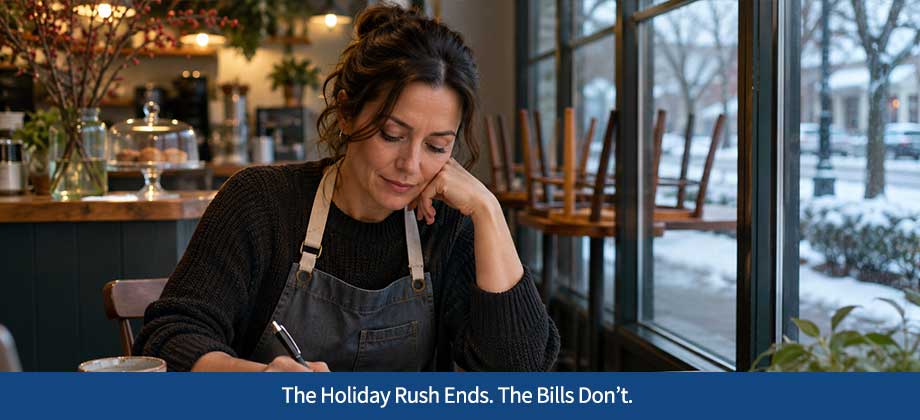
A busy December, a quiet January
For many small businesses, December is the busiest month of the year. The register keeps ringing, tables stay full, and the appointment book has no gaps.
Then January arrives. Shoppers go home with full closets. Diners cut back after the holidays. Clients put off projects until they see their own budgets.
The bills, however, keep their schedule. Payroll still runs every other Friday. Rent is still due on the first. The vendor invoices from your holiday stock orders start coming due.
The good news is that you can see this coming. November is the right time to map out the next few months, while you still have time to make changes.
Why a weekly forecast, and why now
A cash-flow forecast is a simple estimate of the money coming in and going out of your business. Building it week by week, instead of month by month, matters in January.
A monthly view can look fine overall while hiding a tight week. If payroll, rent, and a large vendor bill all land in the same seven days, a month that looks healthy on paper can still leave you short.
Start with the current week in November and carry it through the last week of January. A spreadsheet works well, but a notebook will do the job too.
The four lines every week needs
- Starting cash. The money in your business account at the start of the week. For week one, use your actual bank balance. After that, it is last week’s ending balance.
- Expected deposits. Card sales, cash sales, and customer payments you expect to receive that week. Base these on last January’s sales if you have them, not on December.
- Scheduled expenses. Payroll, rent, vendor invoices, loan payments, utilities, insurance, and any taxes you collected in December that are due in January.
- Ending balance. Starting cash, plus deposits, minus expenses.
Then add the items that are easy to forget after the holidays:
- Returns and refunds. A retailer may refund gift returns in early January. A service business may issue credits for canceled appointments.
- Outstanding vendor invoices. That extra holiday inventory, or the larger food orders a restaurant placed for December parties, may carry 30-day terms that come due in January.
- Payroll timing. Count how many paydays fall in each week. Include seasonal staff and any year-end bonuses on the week they will actually be paid.
Finally, pick a minimum cash balance, the lowest amount you are comfortable keeping on hand. Your forecast will tell you if any week dips below it.
A hypothetical January forecast
Here is how this might look for a made-up neighborhood gift shop. The owner starts January with $32,000 in the bank and has chosen a minimum balance of $15,000. Payroll runs every other week, rent is due in week one, and holiday vendor invoices are spread across the month.
Hypothetical example: expected sales
| Week (2027) | Starting cash | Expected deposits | Returns and refunds | Payroll | Rent | Vendor invoices | Other bills | Ending cash |
| Jan 4–10 | $32,000 | $14,000 | $2,500 | $9,000 | $6,000 | $8,000 | $0 | $20,500 |
| Jan 11–17 | $20,500 | $12,000 | $1,000 | $0 | $0 | $4,000 | $1,500 | $26,000 |
| Jan 18–24 | $26,000 | $11,000 | $500 | $9,000 | $0 | $5,000 | $2,000 | $20,500 |
| Jan 25–31 | $20,500 | $12,000 | $0 | $0 | $0 | $3,000 | $1,500 | $28,000 |
Each week’s ending cash becomes the next week’s starting cash. In this version, the shop never drops below its $15,000 minimum. The tightest weeks are the two payroll weeks, when the balance falls to $20,500.
What if January sales come in 25% lower?
Now test the plan. Suppose a cold snap or a slow economy keeps customers home, and deposits come in 25% below the owner’s estimate. Every bill stays the same.
Hypothetical example: sales 25% below expectations
| Week (2027) | Starting cash | Expected deposits | Total payments out | Ending cash | At or above $15,000? |
| Jan 4–10 | $32,000 | $10,500 | $25,500 | $17,000 | Yes |
| Jan 11–17 | $17,000 | $9,000 | $6,500 | $19,500 | Yes |
| Jan 18–24 | $19,500 | $8,250 | $16,500 | $11,250 | No |
| Jan 25–31 | $11,250 | $9,000 | $4,500 | $15,750 | Yes |
Total payments out include refunds, payroll, rent, vendor invoices, and other bills from the first table.
The week of January 18 is the first week cash falls below the minimum, landing $3,750 short. That is the week with a payroll run and a $5,000 vendor invoice. The balance recovers the following week, so the problem is a short timing gap, not a lasting shortfall.
Seeing this in November gives the owner nearly two months to close that gap.
Five steps to take this November
- Set aside part of December’s receipts. Move a fixed share of each December deposit into a separate account set aside for January bills. In the example, saving about $4,000 across December would cover the gap.
- Confirm vendor due dates. Call or email your suppliers and write down the exact date each holiday invoice is due. Ask whether any due dates can be spread out.
- Adjust January inventory orders. A retailer can trim restock orders for slow-moving items. A restaurant can plan a smaller menu or order more often in smaller amounts.
- Plan January staffing. Decide now when seasonal help will end. A salon or repair shop can match shifts to its booked appointments rather than to December’s pace.
- Update the forecast every week. Swap estimates for actual numbers as they come in. A forecast is most useful when it stays current.
If your forecast shows a gap
A short dip in January is common for seasonal businesses, and spotting it early is a sign of good planning. If your forecast shows a temporary gap, ARF Financial is happy to talk through your working capital, meaning the cash you use to run day-to-day operations. Bring your forecast, and we can look at your options together. There is no obligation, just a conversation about getting through January with confidence.
Your privacy is important to us. ARF Financial will never sell or rent your information to any third party. Click here for more information about our privacy policy.