Holiday Sales Are Up. Why Is Cash Still Tight?
A Great Weekend, Then a Nervous Monday
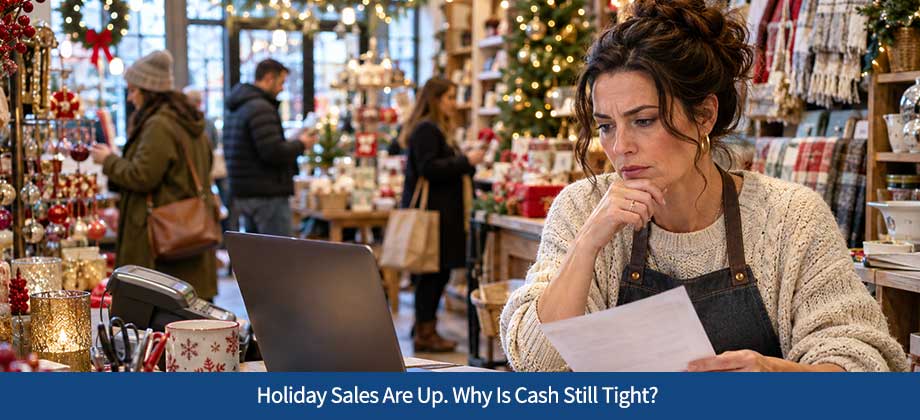
It is Monday morning after a big holiday weekend. The store was busy, online orders kept coming, and your sales report shows one of your best weekends of the year.
Then you open your bank app. Payroll goes out Friday, and you catch yourself doing math in your head to see if the money will be there.
If that sounds familiar, it does not mean something is wrong with your business. Sales and cash are two different things. Your sales report tells you what customers bought. Your bank balance tells you what you can spend today. During the holidays, those two numbers can drift far apart.
Three Reasons Strong Sales Can Still Leave Cash Tight
1. You paid for inventory before it sold
Holiday sales start long before the holidays. To stock shelves and fill the walk-in, you probably bought inventory, packaging, and supplies weeks ago. That money left your account in October or early November.
The sales from that inventory come back slowly, one purchase at a time. So your bank balance can be lower than usual right when sales are at their highest. You are not losing money. You are waiting to earn back money you already spent.
2. Your bills keep a fixed schedule
Payroll does not care how busy the weekend was. It goes out on the same day every pay period, and extra holiday staff can make it bigger than usual. Rent, loan payments, utilities, and vendor invoices also come due on set dates.
Your bills run on the calendar. Your sales run on your customers. When those two schedules do not line up, a gap can open.
3. Some payouts land after the bills are due
A card sale on Saturday is not money you can spend on Saturday. Card processors often deposit funds a business day or more later, so weekend sales may not reach your account until midweek. Online marketplaces can take longer, depending on their payout schedules.
That means one strong weekend can trickle into your bank over the next week or so. If payroll is due before the last deposit arrives, you can come up short even after a record weekend.
Hypothetical Example: A Record Weekend and a Short Friday
This business and these numbers are made up to show how timing works.
Picture a gift shop that sells in its store and through an online marketplace. Over the Black Friday weekend, it rings up $23,000 in sales. On Monday morning it has $9,000 in the bank, and $15,000 in payroll is due Friday.
| Day | Cash in | Cash out | Ending balance |
| Mon., Nov. 30 (start) | $9,000 | ||
| Mon., Nov. 30 | $3,000 cash deposit from weekend register sales | $12,000 | |
| Tue., Dec. 1 | $7,000 card payout for Friday and Saturday sales | $8,000 holiday inventory reorder | $11,000 |
| Wed., Dec. 2 | $2,000 shipping boxes and packaging | $9,000 | |
| Thu., Dec. 3 | $4,000 card payout for Sunday sales | $13,000 | |
| Fri., Dec. 4 | $15,000 payroll | -$2,000 | |
| Mon., Dec. 7 | $9,000 marketplace payout for weekend online sales | $7,000 |
Here is the math. The shop starts with $9,000 and collects $14,000 before Friday, for $23,000. It pays $10,000 for inventory and supplies, leaving $13,000. Payroll of $15,000 puts it $2,000 short on Friday.
That gap lasts three days, until the $9,000 marketplace payout arrives on Monday. Every dollar of the weekend’s $23,000 reaches the bank by Dec. 7. The shop has a timing problem, not a sales problem.
To keep things simple, this example leaves out processing fees, which would make each payout a bit smaller.
Your Cash Gap Checklist for This Week
Set aside 20 minutes and work through these steps.
- ☐ Check what is actually in the bank. Use today’s available balance, not your sales report or deposits marked pending.
- ☐ Find your next major bill. Write down the date and amount of payroll, rent, or your largest vendor payment.
- ☐ List what will clear before that date. Check your card processor and marketplace accounts for expected payout dates. Count only deposits that land before the bill is due.
- ☐ Do the simple math. Today’s balance, plus deposits that clear in time, minus bills due before then. If the answer is near zero or below, plan for it now.
- ☐ Look for expenses you can time differently. Could a supply order wait a week? Could you ask a vendor about a later due date, or split a large order into two deliveries?
- ☐ Run the check again next week. A timing gap can show up more than once during the season.
When the Gap Keeps Coming Back
A one-time gap can often be handled by moving a bill or delaying a purchase. If the same gap shows up week after week, it may help to talk it through with someone who looks at small business cash flow every day.
ARF Financial is glad to walk through your payout timing and bill schedule with you, with no pressure and no obligation. If it makes sense, we can talk about options that may fit your business. Reach out whenever you are ready.
Your privacy is important to us. ARF Financial will never sell or rent your information to any third party. Click here for more information about our privacy policy.